
Your Annual Pension Statement (Deferred Members)
Each year, SHEPP provides all deferred Plan members with an Annual Pension Statement. This statement summarizes the benefit entitlement you have earned upon termination with all SHEPP employers. Review it carefully and keep it handy. You can also download a copy of your most recent statement on SHEPPweb.
If any of your personal information changes, be sure to update your member record by signing in to SHEPPweb or contacting our office.
Your statement includes a lot of information, so we’ve provided a guide to understanding it below.
Your Annual Pension Statement Guide
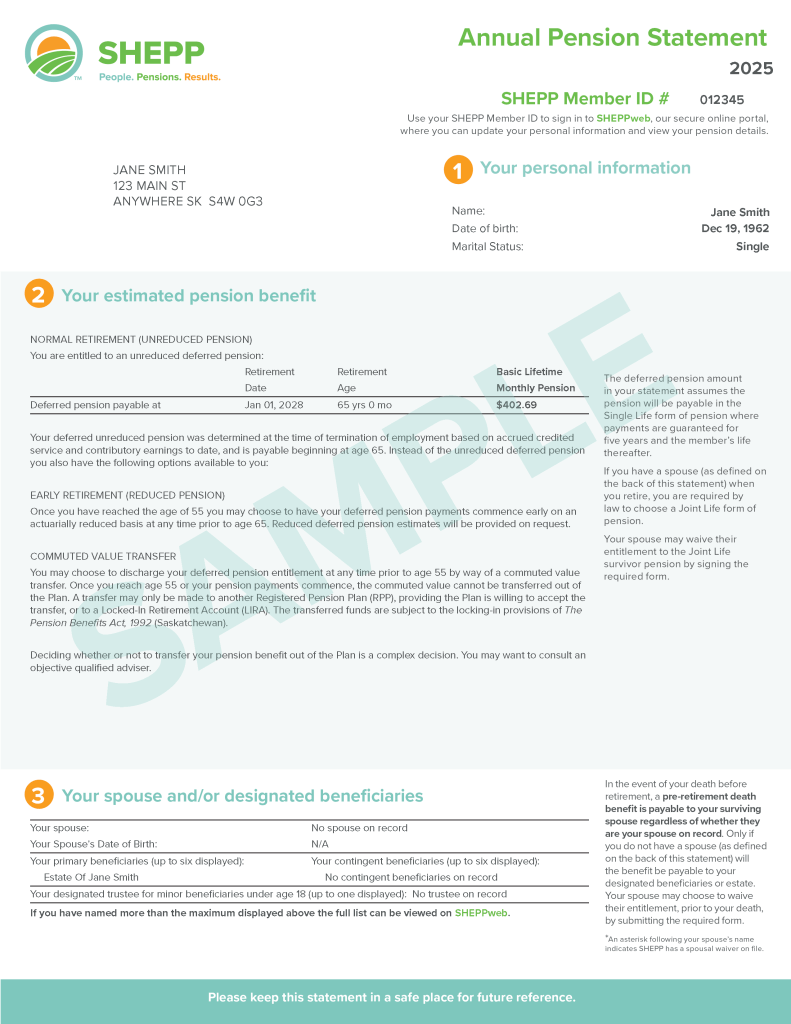
Note: Your SHEPP Member ID # is also your USERNAME to sign in to SHEPPweb!
1. Your personal information
SHEPP uses your date of birth to determine your normal and early retirement dates.
If you have a spouse as defined by The Pension Benefits Act, 1992 (Saskatchewan) they are legally entitled to certain benefits under the Plan. Your spouse’s date of birth may have an effect on the amount of a Joint Life form of pension.
For more information on spousal rights, visit the Marriage page.
2. Your estimated monthly pension benefit
The Normal Retirement (Unreduced Pension) is the estimated amount you are eligible to receive beginning on the first of the month that coincides with or immediately follows your 65th birthday. This gross amount is calculated using SHEPP’s benefit formula which takes into account your average contributory earnings and credited service as of the date you terminated employment with your SHEPP employer. It’s based on a Single Life form of pension guaranteed for 5 years.
At retirement, you will have a number of different forms of pension to choose from. In a Single Life form of pension, if you die before the end of the guarantee term, your pension will continue to your beneficiary or estate until the end of the term. Guarantee terms begin on your retirement date.
If you have a spouse when you retire, you are required by law to choose a Joint Life form of pension, where no less than 60% of your pension is payable to your spouse for their lifetime, upon your death. Your spouse may waive their entitlement to the Joint Life survivor pension by signing the required form. For more information, visit the Choosing a Form of Pension page.
Once you reach the age of 55, you may choose an Early Retirement (Reduced Pension) in which you begin receiving actuarially reduced pension payments before the normal retirement age of 65. Please contact SHEPP to request a pension estimate based on an early retirement date.
You may also choose to transfer your SHEPP benefit out of the Plan through a Commuted Value Transfer. At any time before the
age of 55, you may choose to transfer the commuted value of your SHEPP pension to a Locked-In Retirement Account (LIRA) or another Registered Pension Plan (RPP) provided that plan accepts the transfer. For more information, refer to the Commuted Value Transfer Information Sheet.
3. Your spouse and/or designated beneficiaries
Your designated beneficiaries may be entitled to a pre-retirement death benefit upon your death if you do not have a spouse or your
spouse has waived their right to the death benefit. For more information, visit the Your Beneficiaries page.